Czech Tax Residency: 183-Day Rule, Treaties and US Citizens
Popular
You are a Czech tax resident if you have a home in Czechia where you intend to live (bydliště) or spend at least 183 days here in a calendar year; one test is enough (Section 2 of the Income Tax Act, 586/1992 Sb.). Every started day counts, and reaching 183 days makes you resident for the whole year, back to January 1. Residents pay Czech tax on worldwide income, non-residents only on Czech-source income. If another country also claims you, the tax treaty decides: permanent home, then center of vital interests, habitual abode and citizenship. A certificate of tax residence costs 100 Kč. US citizens remain taxable in the US on worldwide income. Around Prague checked the law, the guidance of the Czech General Financial Directorate (GFŘ), the Ministry of Finance treaty list and the IRS and FinCEN websites on November 10, 2026.
The two tests: a home or 183 days
The GFŘ guidance for 2026 says the tests are independent; neither takes priority.
| Test | What counts | Proof | Law |
|---|---|---|---|
| Home (bydliště) | A permanent home (stálý byt), owned or rented, available at any time, in circumstances that show you intend to stay. The GFŘ says even a dormitory, a rented room, a hotel or an Airbnb can qualify, e.g. for a new employee still looking for a flat. Residence starts the day you have the home | Lease or purchase contract; family, job, school, bank accounts here | Section 2(2), 2(4) |
| 183 days (obvyklé zdržování) | At least 183 days in a calendar year, in one stay or several. Every started day counts, including arrival and departure days | Bank statements, tickets, accommodation records, your own log | Section 2(4) |
Per the GFŘ, your residence permit date, labor office registration and health insurer do not matter. A visa or permanent residency (trvalý pobyt) is an immigration status, not a tax status. The burden of proof is on you.
Students and patients. People in Czechia only to study or to receive medical treatment are non-residents even after 183 days (Section 2(3)). The GFŘ adds that the exception ends once they take a job or start a business.
What being a Czech tax resident means
- Residents owe Czech tax on income from Czech and foreign sources (Section 2(2)): salary, self-employment (OSVČ) income, rent, interest, dividends, gains on shares and crypto.
- Non-residents owe Czech tax only on the Czech-source income listed in Section 22.
- Double taxation is removed under the treaty with the other country (Section 38f(1)), by a credit (zápočet) or an exemption (vynětí). Foreign tax is proven with a certificate from the foreign tax authority (Section 38f(5)).
For remote workers, freelancers with foreign clients and digital nomads this means foreign income is taxable here too, subject to the treaty. See our guides on the Czech tax return, the trade license, the flat-rate tax, crypto tax and investing.
Arriving or leaving mid-year
Example: you arrive on April 1, 2026, and rent a flat. Under the home test you are resident from April 1. If you stay, September 30 is your 183rd day, and Czech law then treats you as resident for all of 2026, from January 1 (GFŘ). When you leave, it works the other way: after 183 days you stay resident under Czech law until December 31.
If another country also claims you for the same months, the treaty splits the year. In the GFŘ example from Ukraine, a mother who arrived on April 1, 2022, was a Ukrainian resident under the treaty until March 31 and a Czech resident from April 1.
Dual residence and the treaty tie-breakers
The GFŘ uses two steps: Czech law first, and the treaty only if the other country also treats you as resident under its own law. Residence may never be decided on treaty criteria alone. Most treaties list the tie-breakers in Article 4; each applies only if the one before gives no answer:
- Permanent home in only one country.
- Center of vital interests: with a home in both, closer personal and economic ties (family, work, property).
- Habitual abode: where you usually stay.
- Citizenship.
The Ministry of Finance lists treaties with 100 countries as of November 2, 2026, including the United States, the United Kingdom, Canada, Ireland, Australia, Germany, Austria, Poland, Slovakia and Ukraine. This guide is not tax advice: in a dispute the tax office decides, and you bring the evidence.
Certificate of tax residence: step by step
The certificate (potvrzení o daňovém domicilu) proves Czech residence abroad, typically so a treaty can be applied. According to the GFŘ:
- Apply to your local tax office (místně příslušný finanční úřad, Section 13 of the Tax Procedure Code).
- There is no set form. The GFŘ's English and Ukrainian sample requests are for orientation only; you must file in Czech (Section 76 of the Tax Procedure Code), in writing, orally for the record, via data box (datová schránka), by signed email or with the "Obecná písemnost" e-form on the tax portal.
- Name the country. For treaty countries the office issues form MF 25 5232 or confirms the foreign authority's form (with a Czech translation).
- Expect questions about your arrival, days in Czechia, type of stay, homes here and abroad, family, income, insurance and bank accounts.
- Pay 100 Kč (about $5 at the Czech National Bank rate of 21.702 CZK per dollar on November 10, 2026) per original, in cash, by transfer or by QR code in the MOJE daně portal. Filing and a refusal are free.
The certificate is issued as of a specific date (no later than the day of issue) or for a past tax year or part of it, never for the current year as a whole: a certificate for all of 2026 is available only after December 31. The GFŘ gives no processing deadline, and a refusal cannot be appealed.
US citizens in Czechia
The IRS states that US citizens abroad are taxed on worldwide income from all sources. The US–Czech treaty (1993, published in Czechia as 32/1994 Sb.) keeps it that way:
- Saving clause, Article 1(3): each country may tax its residents and citizens, including former citizens, "as if the Convention had not come into effect."
- Article 4(2)(c): Czechia treats a US citizen or green card holder as a US resident only with a substantial presence, permanent home or habitual abode in the US.
- Article 4(4): permanent home, center of vital interests, habitual abode, citizenship; for a citizen of both countries or neither, mutual agreement of the tax authorities. In a GFŘ example, a US citizen who worked in Czechia all of 2024 and lived here with the family was a Czech resident under the treaty.
- Article 24: Czechia credits US tax only where it is not imposed solely on the basis of citizenship (24(2)). For a US citizen resident in Czechia, income the US taxes only because of citizenship is treated as arising in Czechia to the extent needed to avoid double tax, but US tax may not fall below what a non-citizen would pay (24(3)).
- Article 19(1)(b): US Social Security paid to a Czech resident is taxable only in the US.
| IRS and FinCEN | Rule |
|---|---|
| Tax return | Required; the FEIE and foreign tax credit apply only if you file. Living abroad gives an automatic extension to June 15 (attach a statement); interest runs from April 15 |
| Foreign earned income exclusion (Form 2555) | Up to $130,000 for 2025 and $132,900 for 2026, per person. Needs a foreign tax home plus bona fide residence for a full tax year or 330 full days abroad in 12 consecutive months. Does not reduce self-employment tax or cover pensions |
| Foreign tax credit (Form 1116) | Credit or itemized deduction for Czech tax; no credit on income excluded under the FEIE |
| FBAR (FinCEN Form 114) | Foreign accounts together above $10,000 at any time in the year. Filed with FinCEN, not the IRS; due April 15, automatic extension to October 15 |
| Form 8938 | Living abroad: single or married filing separately above $200,000 on December 31 or $300,000 at any time; married filing jointly $400,000 or $600,000. Penalty up to $10,000, plus up to $50,000 after an IRS notice |
Czech Tax Residency (FAQ)
How many days make you a Czech tax resident?
183 days in a calendar year, in one stretch or added up; every started day counts. A home here where you intend to live makes you resident sooner.
Does a Czech residence permit make me a tax resident?
No. According to the GFŘ, the permit date does not matter; only your home and the days you actually spend here count.
Can I get a Czech tax residence certificate for 2026 now?
Only as of a specific date up to the day of issue; for the whole of 2026, after the year ends. The fee is 100 Kč.
Do I still file a US return if I am a Czech resident?
Yes. The saving clause lets the US tax its citizens as if the treaty did not exist; the FEIE or the foreign tax credit reduces US tax only if you file.
Sources: Income Tax Act 586/1992 Sb., Sections 2, 22, 38f, GFŘ: determining tax residence of individuals (2026, in Czech), GFŘ: certificates of tax residence, Ministry of Finance: treaties in force, US–Czech income tax treaty (IRS), IRS: US citizens abroad, IRS: foreign earned income exclusion, IRS: FEIE amounts, IRS: foreign tax credit, IRS: June 15 extension, FinCEN: FBAR, IRS: Form 8938 and FBAR. Checked on November 10, 2026.
See also: Tax Return in Czechia, Tax Refunds in Czechia, Flat-Rate Tax for OSVČ, How to Get a Trade License, Health Insurance for Foreigners, Czech Digital Nomad Visa, Crypto Tax in Czechia, Investing as a Foreigner, Sending Money Abroad, Permanent Residency in Czechia.
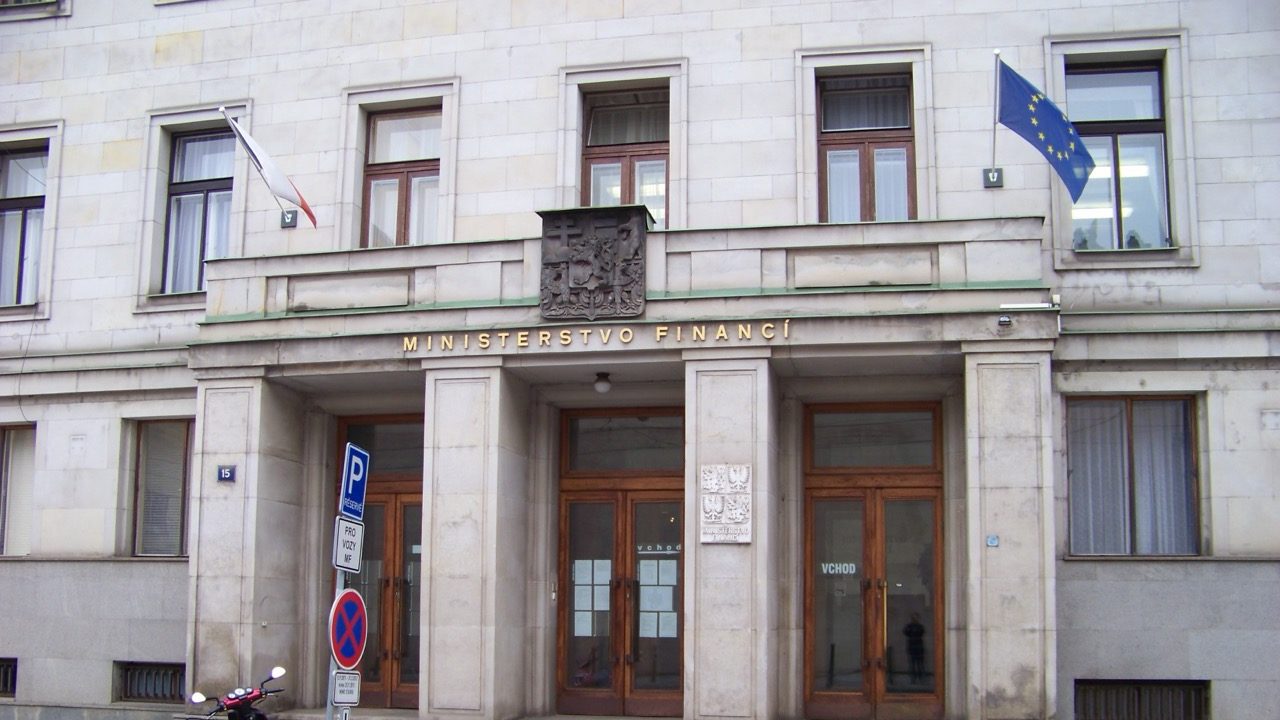
Photo: entrance to the Czech Ministry of Finance on Letenská Street in Prague. ŠJů, Wikimedia Commons, CC BY-SA 3.0.
Comments (0)
Please be polite. Spam and insults will be removed.