Michal Semotan goes to the mountains to build a new PPF portfolio
USD 21,52
Popular
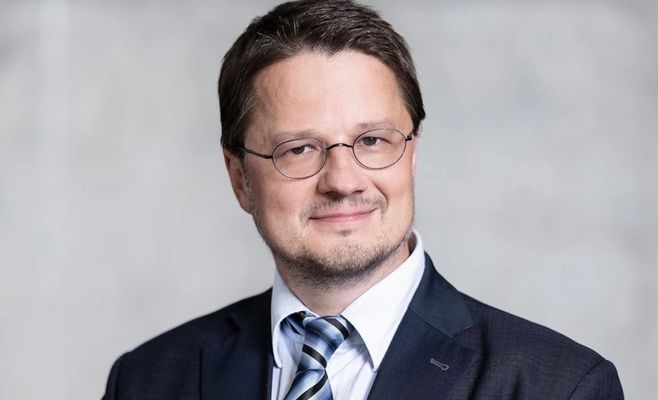
Michal Semotan, for years the public face of J&T's investment division, is now building a new investment strategy for the PPF group — quite literally from scratch, with not a single inherited position in the portfolio. He talked about how this unusual process is going on the Money Maker Hedge podcast.
After moving from J&T to PPF, Semotan found himself in a situation rare for an investor: the company is still waiting for a licence from the Czech National Bank, and for now the portfolio manager has no assets under management at all. “It's a pretty strange feeling, it took me a while to get used to it,” he admitted.
According to him, the main difference in his new situation is the chance to look at the market from the outside, without being tied to constantly watching quotes and CNBC. To think through the concept of the future portfolio, Semotan gave himself four days of solitude in the mountains — alone, with a view of Sněžka. The result wasn't a list of specific stocks but a sharper principle: the new portfolio will be narrower and more concentrated than his previous ones.
At the same time, he has no intention of completely changing his investment style: “I can't be a completely different Semotan — that just wouldn't be me,” he said, adding that some positions will still overlap with his portfolios from his J&T days.
Among today's strongest ideas, the investor named two assets he considers “almost a necessity” — NVIDIA and Micron — citing their rapid growth in performance and Nvidia's plans to double chip sales next year. The second strategic direction is energy, including ČEZ, amid rising electricity demand driven by data centre construction.
One particular challenge for the manager is coming to terms psychologically with a much higher entry price: Micron shares, which Semotan used to buy at far lower prices, are now trading above a thousand dollars, compared with around 300 at the start of the year. He admits that after four years of gains on the US indices, entering the market isn't easy, and doesn't rule out that a modest correction before the end of the year could offer a chance to buy assets more cheaply.